August 26, 2026, 07:14

Views:
1459
Driver assistance
RF services
CASCO in Russia: car protection now available through GreenGo

GreenGo Editorial Team
The material has been reviewed and prepared by the GreenGo team
Table of contents
- What is CASCO
- How CASCO differs from OSAGO
- What risks CASCO can protect against
- What types of CASCO exist
- What is a deductible in CASCO
- What the cost of CASCO depends on
- What documents may be needed
- Who especially needs CASCO
- How to get CASCO through GreenGo
- Advantages of CASCO for GreenGo partners
- Summary
GreenGo continues to expand its line of insurance products for partners. Now the platform offers Russian CASCO — voluntary insurance that allows you to protect your car from financial losses in case of damage, theft, and other events specified in the contract.
Unlike OSAGO, which protects the driver's liability to other road users, CASCO is designed to protect the vehicle itself. Depending on the selected program, the policy may cover the consequences of accidents, theft, total loss of the vehicle, fire, natural disasters, falling objects, and other risks. The exact list is always determined by the terms of a specific insurance contract.
For GreenGo partners, the new product is an opportunity to offer the client more comprehensive vehicle protection and select insurance that meets their needs.
Unlike OSAGO, which protects the driver's liability to other road users, CASCO is designed to protect the vehicle itself. Depending on the selected program, the policy may cover the consequences of accidents, theft, total loss of the vehicle, fire, natural disasters, falling objects, and other risks. The exact list is always determined by the terms of a specific insurance contract.
For GreenGo partners, the new product is an opportunity to offer the client more comprehensive vehicle protection and select insurance that meets their needs.
What is CASCO
CASCO is voluntary vehicle insurance against property risks. Unlike mandatory OSAGO, the vehicle owner independently decides whether to purchase such protection and selects a suitable program.
The main task of CASCO is to compensate the owner's financial losses if an event covered by the contract occurs with the insured vehicle.
For example, a vehicle may be damaged in an accident, suffer from fire or a natural disaster, or be stolen. Depending on the program, the insurer arranges repairs or pays insurance compensation in accordance with the contract terms.
However, there is no single set of risks for all insurers. Since CASCO is voluntary insurance, the list of insured events, limitations, and coverage amounts are determined by the specific contract.
Important: before purchasing CASCO, it is necessary to carefully study the terms of the selected program — which risks are included, which events are excluded, whether a deductible is provided, and how insurance compensation is paid.
The main task of CASCO is to compensate the owner's financial losses if an event covered by the contract occurs with the insured vehicle.
For example, a vehicle may be damaged in an accident, suffer from fire or a natural disaster, or be stolen. Depending on the program, the insurer arranges repairs or pays insurance compensation in accordance with the contract terms.
However, there is no single set of risks for all insurers. Since CASCO is voluntary insurance, the list of insured events, limitations, and coverage amounts are determined by the specific contract.
Important: before purchasing CASCO, it is necessary to carefully study the terms of the selected program — which risks are included, which events are excluded, whether a deductible is provided, and how insurance compensation is paid.
How CASCO differs from OSAGO
CASCO and OSAGO protect against different financial risks, so one policy is not a replacement for the other.
If the driver becomes at fault in an accident, OSAGO compensates the injured party within established limits. The at-fault driver's own vehicle repair is not covered by their OSAGO.
CASCO, on the other hand, can provide protection for the vehicle itself, including when the accident was caused by the owner, if the corresponding event is covered by the contract.
This is why many car owners use both types of insurance simultaneously.
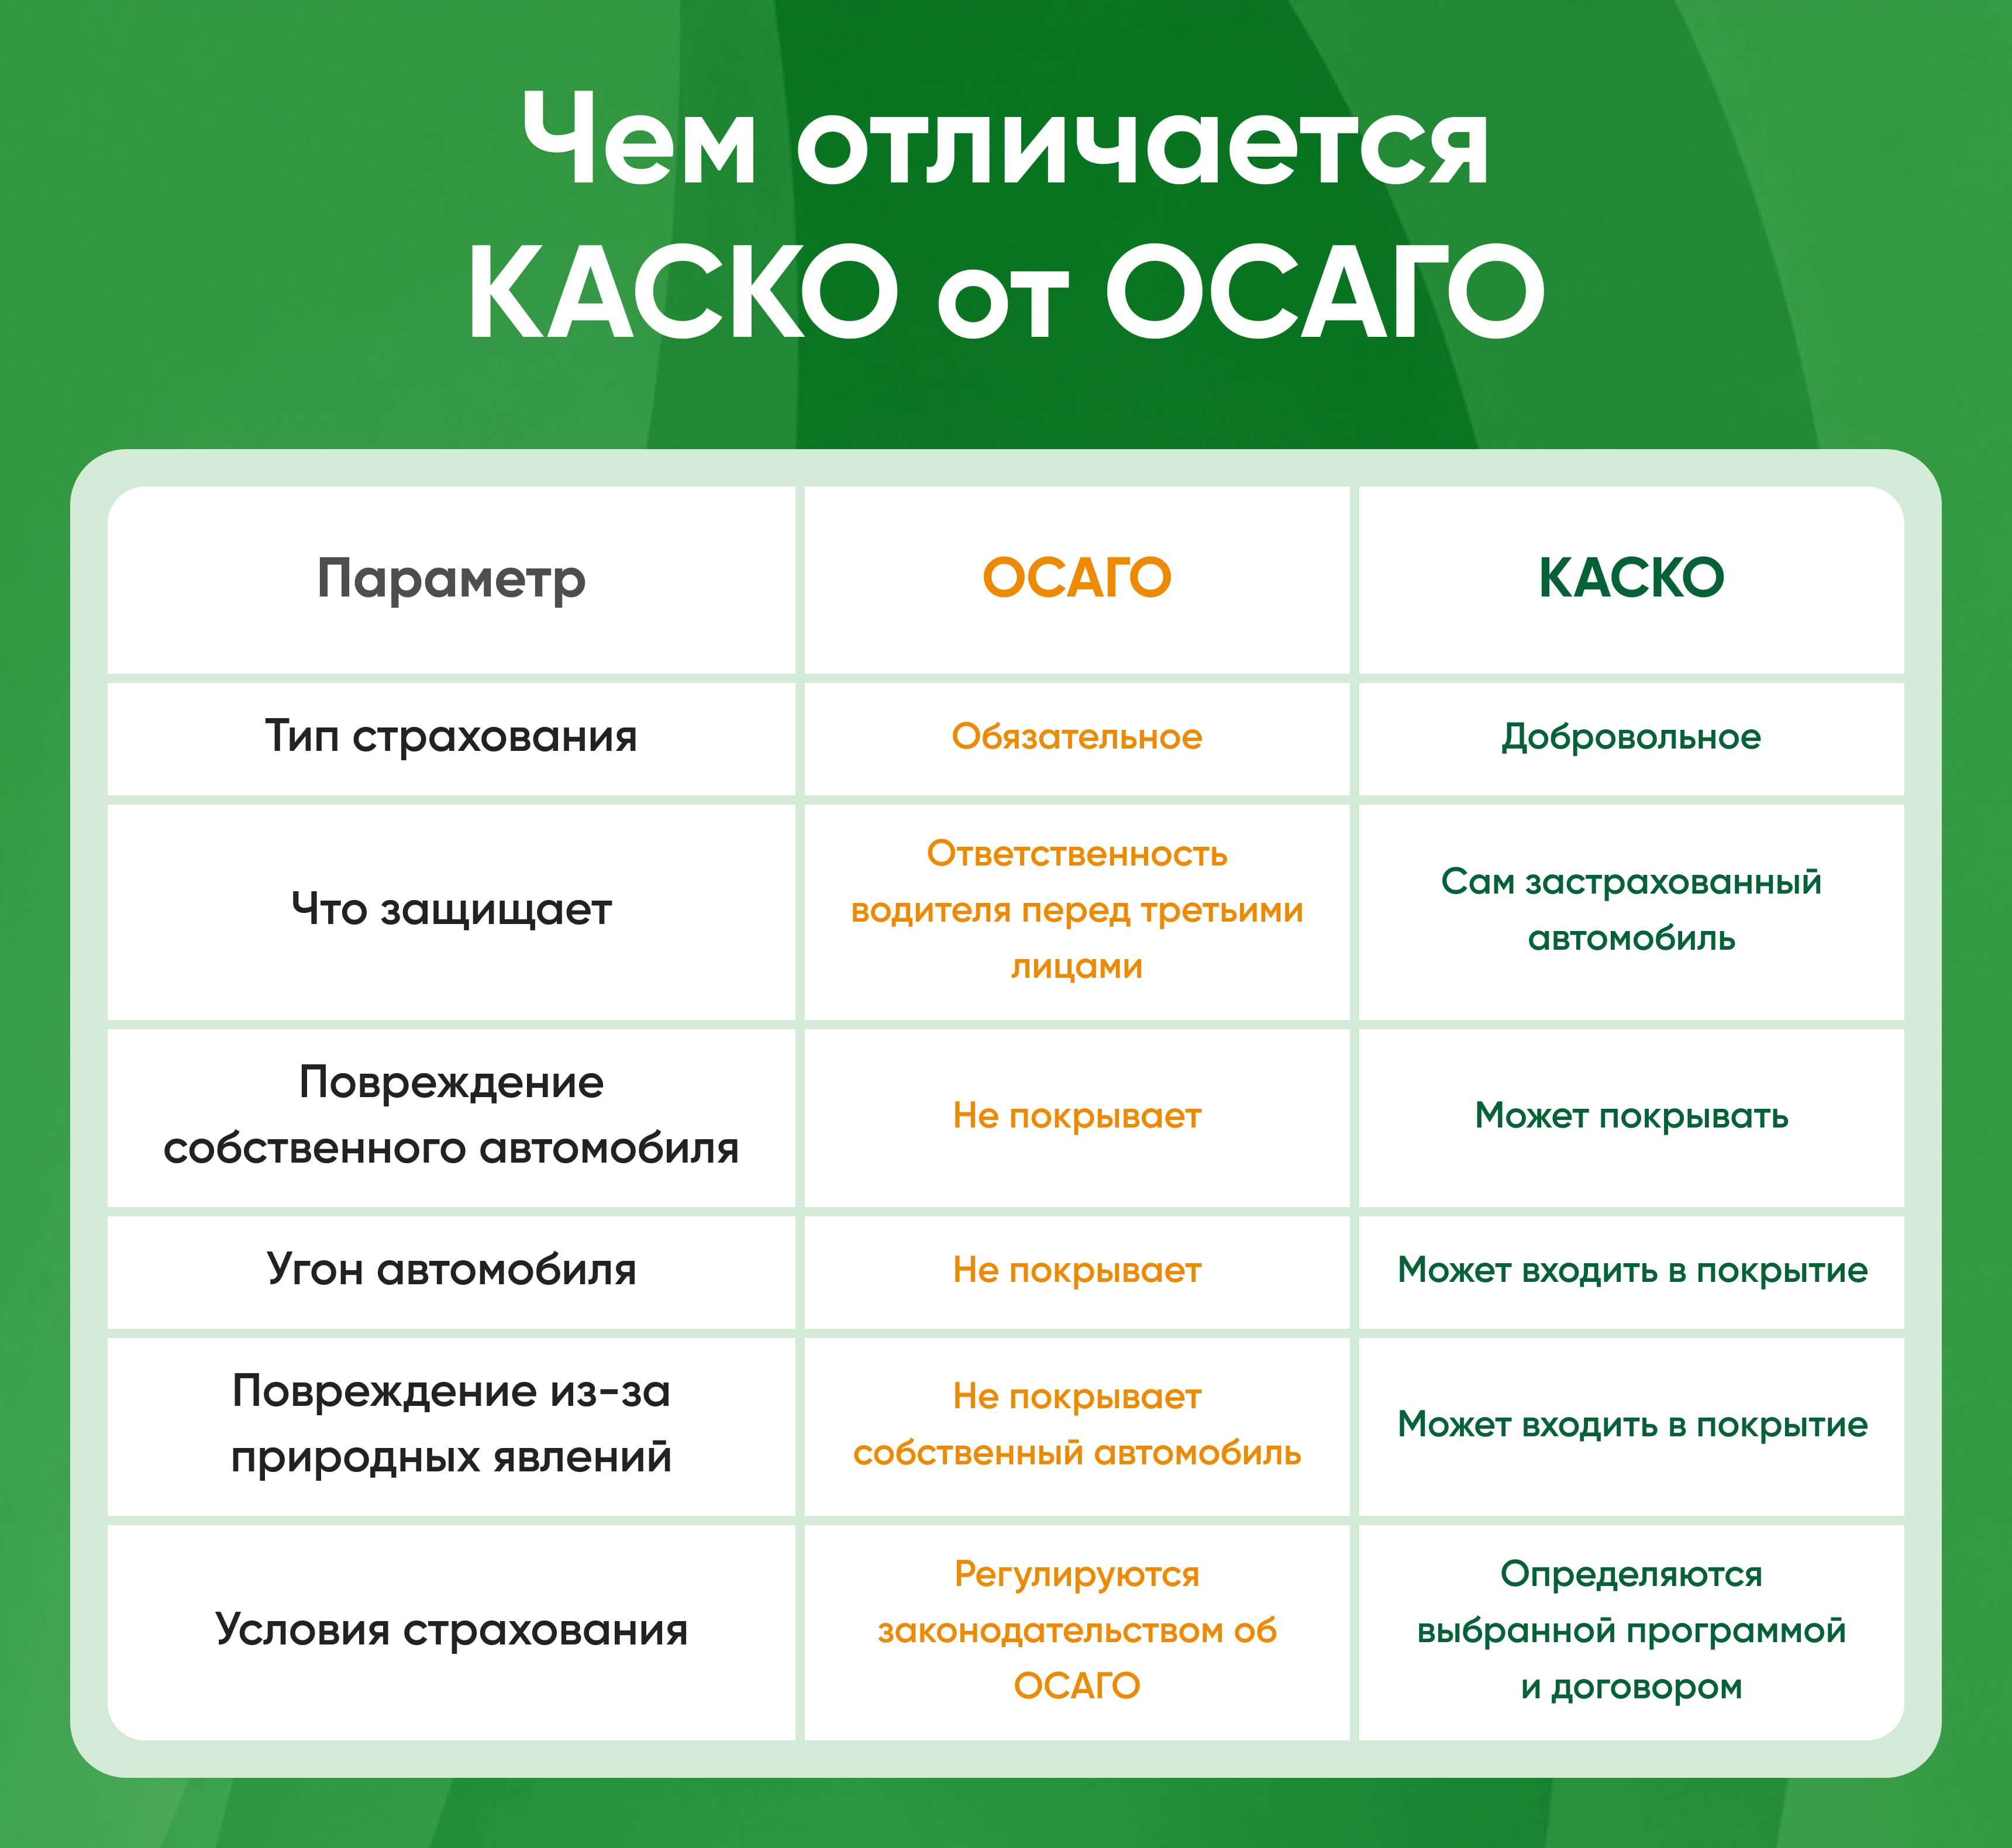
| Parameter | OSAGO | CASCO |
|---|---|---|
| Type of insurance | Mandatory | Voluntary |
| What it protects | Driver's liability to third parties | The insured vehicle itself |
| Damage to own vehicle | Not covered | May be covered |
| Vehicle theft | Not covered | May be included in coverage |
| Damage due to natural phenomena | Does not cover own vehicle | May be included in coverage |
| Insurance terms | Governed by OSAGO legislation | Determined by the selected program and contract |
If the driver becomes at fault in an accident, OSAGO compensates the injured party within established limits. The at-fault driver's own vehicle repair is not covered by their OSAGO.
CASCO, on the other hand, can provide protection for the vehicle itself, including when the accident was caused by the owner, if the corresponding event is covered by the contract.
This is why many car owners use both types of insurance simultaneously.
What risks CASCO can protect against
The set of insurance risks depends on the program of a specific insurance company. Common coverage options include:
For example, Russian CASCO programs may include protection against accidents, theft, fire, explosion, natural disasters, falling objects, and a number of other events. However, the presence of each risk must be verified under the terms of the selected policy.
- Accidents;
- Theft or hijacking of the vehicle;
- Total loss of the vehicle;
- Fire or explosion;
- Natural disasters;
- Falling trees, ice, snow, and other objects;
- Unlawful actions of third parties;
- Damage from stones and other objects thrown from under wheels;
- Other risks specified in the contract.
For example, Russian CASCO programs may include protection against accidents, theft, fire, explosion, natural disasters, falling objects, and a number of other events. However, the presence of each risk must be verified under the terms of the selected policy.
What types of CASCO exist
CASCO can be selected to suit different client needs. It is not necessary to purchase the maximum set of risks every time.
Programs can be conditionally divided as follows:
Specific program names and terms differ among insurers.
This allows selecting an option based on vehicle cost, usage features, and client budget.
Programs can be conditionally divided as follows:
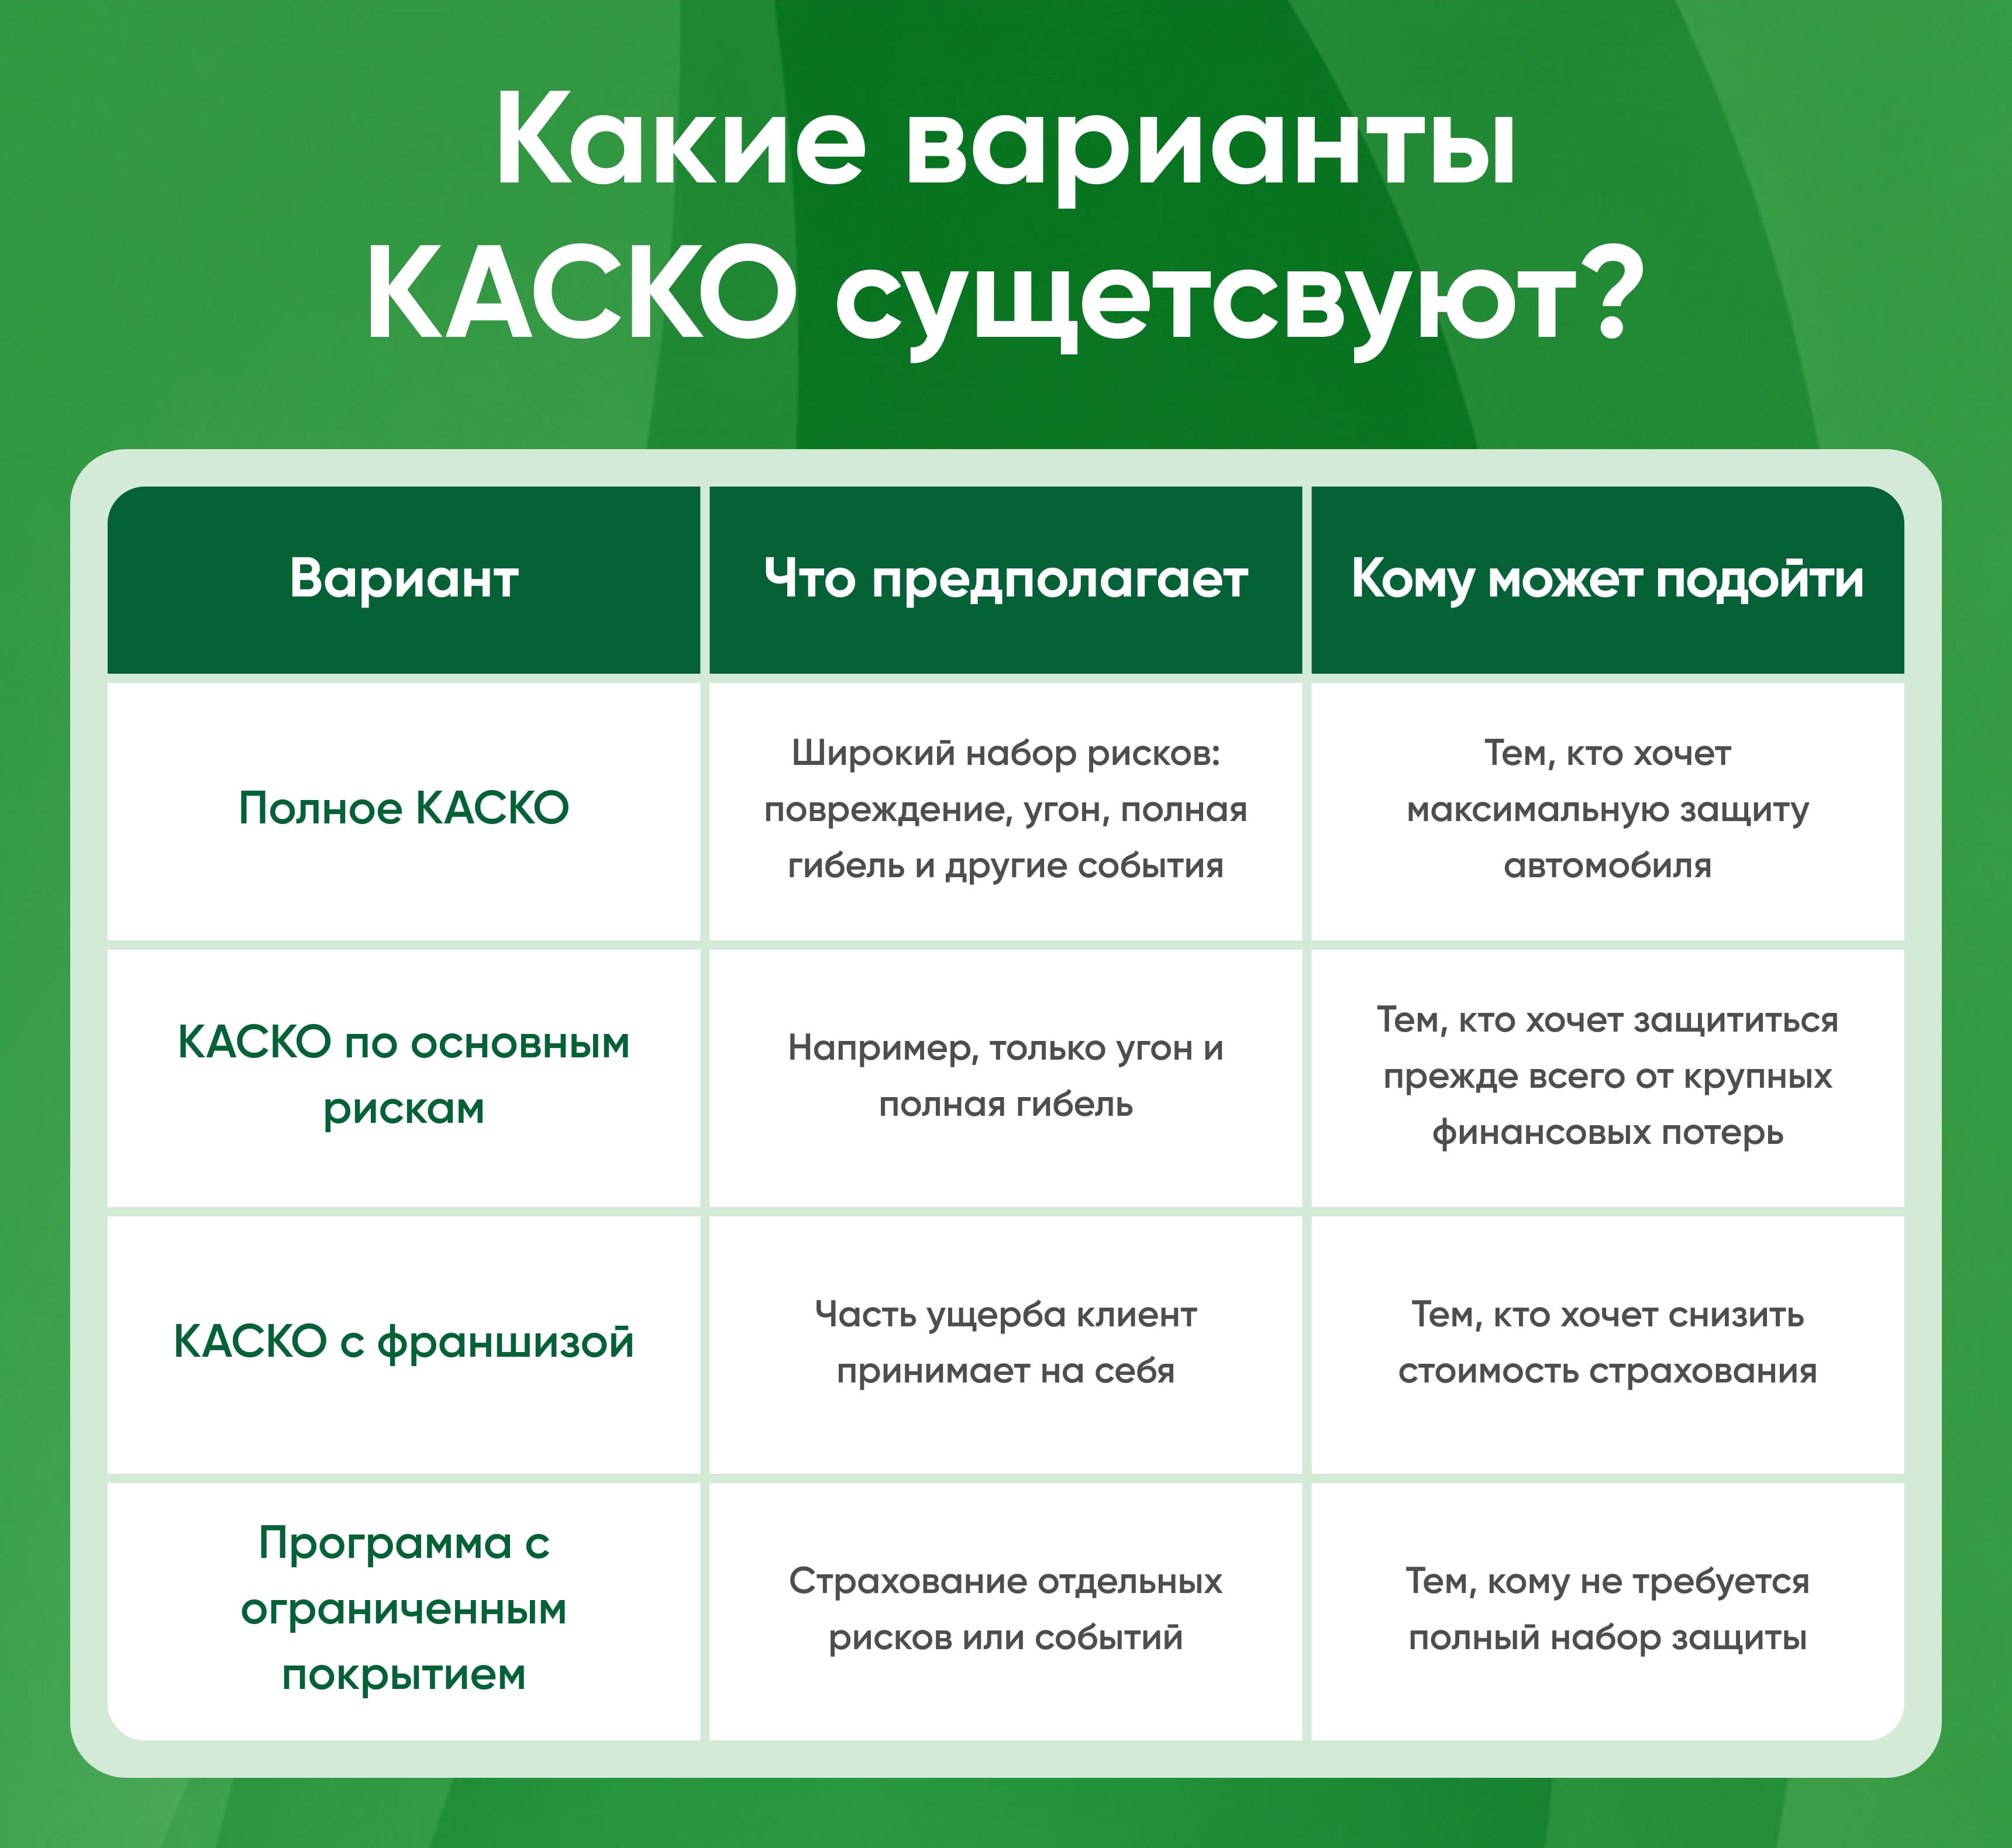
| Type | What it includes | Who it may suit |
|---|---|---|
| Full CASCO | Wide range of risks: damage, theft, total loss, and other events | Those who want maximum vehicle protection |
| CASCO for basic risks | For example, only theft and total loss | Those who want to protect against major financial losses |
| CASCO with deductible | The client accepts part of the damage | Those who want to reduce insurance costs |
| Limited coverage program | Insurance for specific risks or events | Those who do not need a full set of protection |
Specific program names and terms differ among insurers.
This allows selecting an option based on vehicle cost, usage features, and client budget.
What is a deductible in CASCO
When selecting a program, a client may encounter the concept of a "deductible."
A deductible is the portion of the loss specified in the contract that the client accepts in the event of an insurance claim.
For example, if the contract includes a deductible, the insurance compensation is calculated taking into account its size and application terms.
Why is it needed? Primarily — to manage the policy cost. Programs with a deductible are usually cheaper since part of the risk remains with the vehicle owner.
This option may be interesting for an experienced driver who is willing to pay for minor damages out of pocket but wants to protect the vehicle from serious financial losses.
A deductible is the portion of the loss specified in the contract that the client accepts in the event of an insurance claim.
For example, if the contract includes a deductible, the insurance compensation is calculated taking into account its size and application terms.
Why is it needed? Primarily — to manage the policy cost. Programs with a deductible are usually cheaper since part of the risk remains with the vehicle owner.
This option may be interesting for an experienced driver who is willing to pay for minor damages out of pocket but wants to protect the vehicle from serious financial losses.
What the cost of CASCO depends on
Unlike OSAGO, the cost of CASCO is not calculated using a single market-wide tariff.
The price may be influenced by:
Therefore, the cost of two CASCO policies for similar vehicles may differ.
The optimal approach is not to focus only on the lowest price, but to directly compare insurance coverage terms.
The price may be influenced by:
- Vehicle make and model;
- Year of manufacture;
- Vehicle cost;
- Driver age and qualifications;
- Selected set of risks;
- Presence and size of the deductible;
- Additional options;
- Vehicle usage conditions;
- Specific insurance company requirements.
Therefore, the cost of two CASCO policies for similar vehicles may differ.
The optimal approach is not to focus only on the lowest price, but to directly compare insurance coverage terms.
What documents may be needed
The exact list of documents depends on the insurer's requirements and the selected program.
Typically, the following are used during processing:
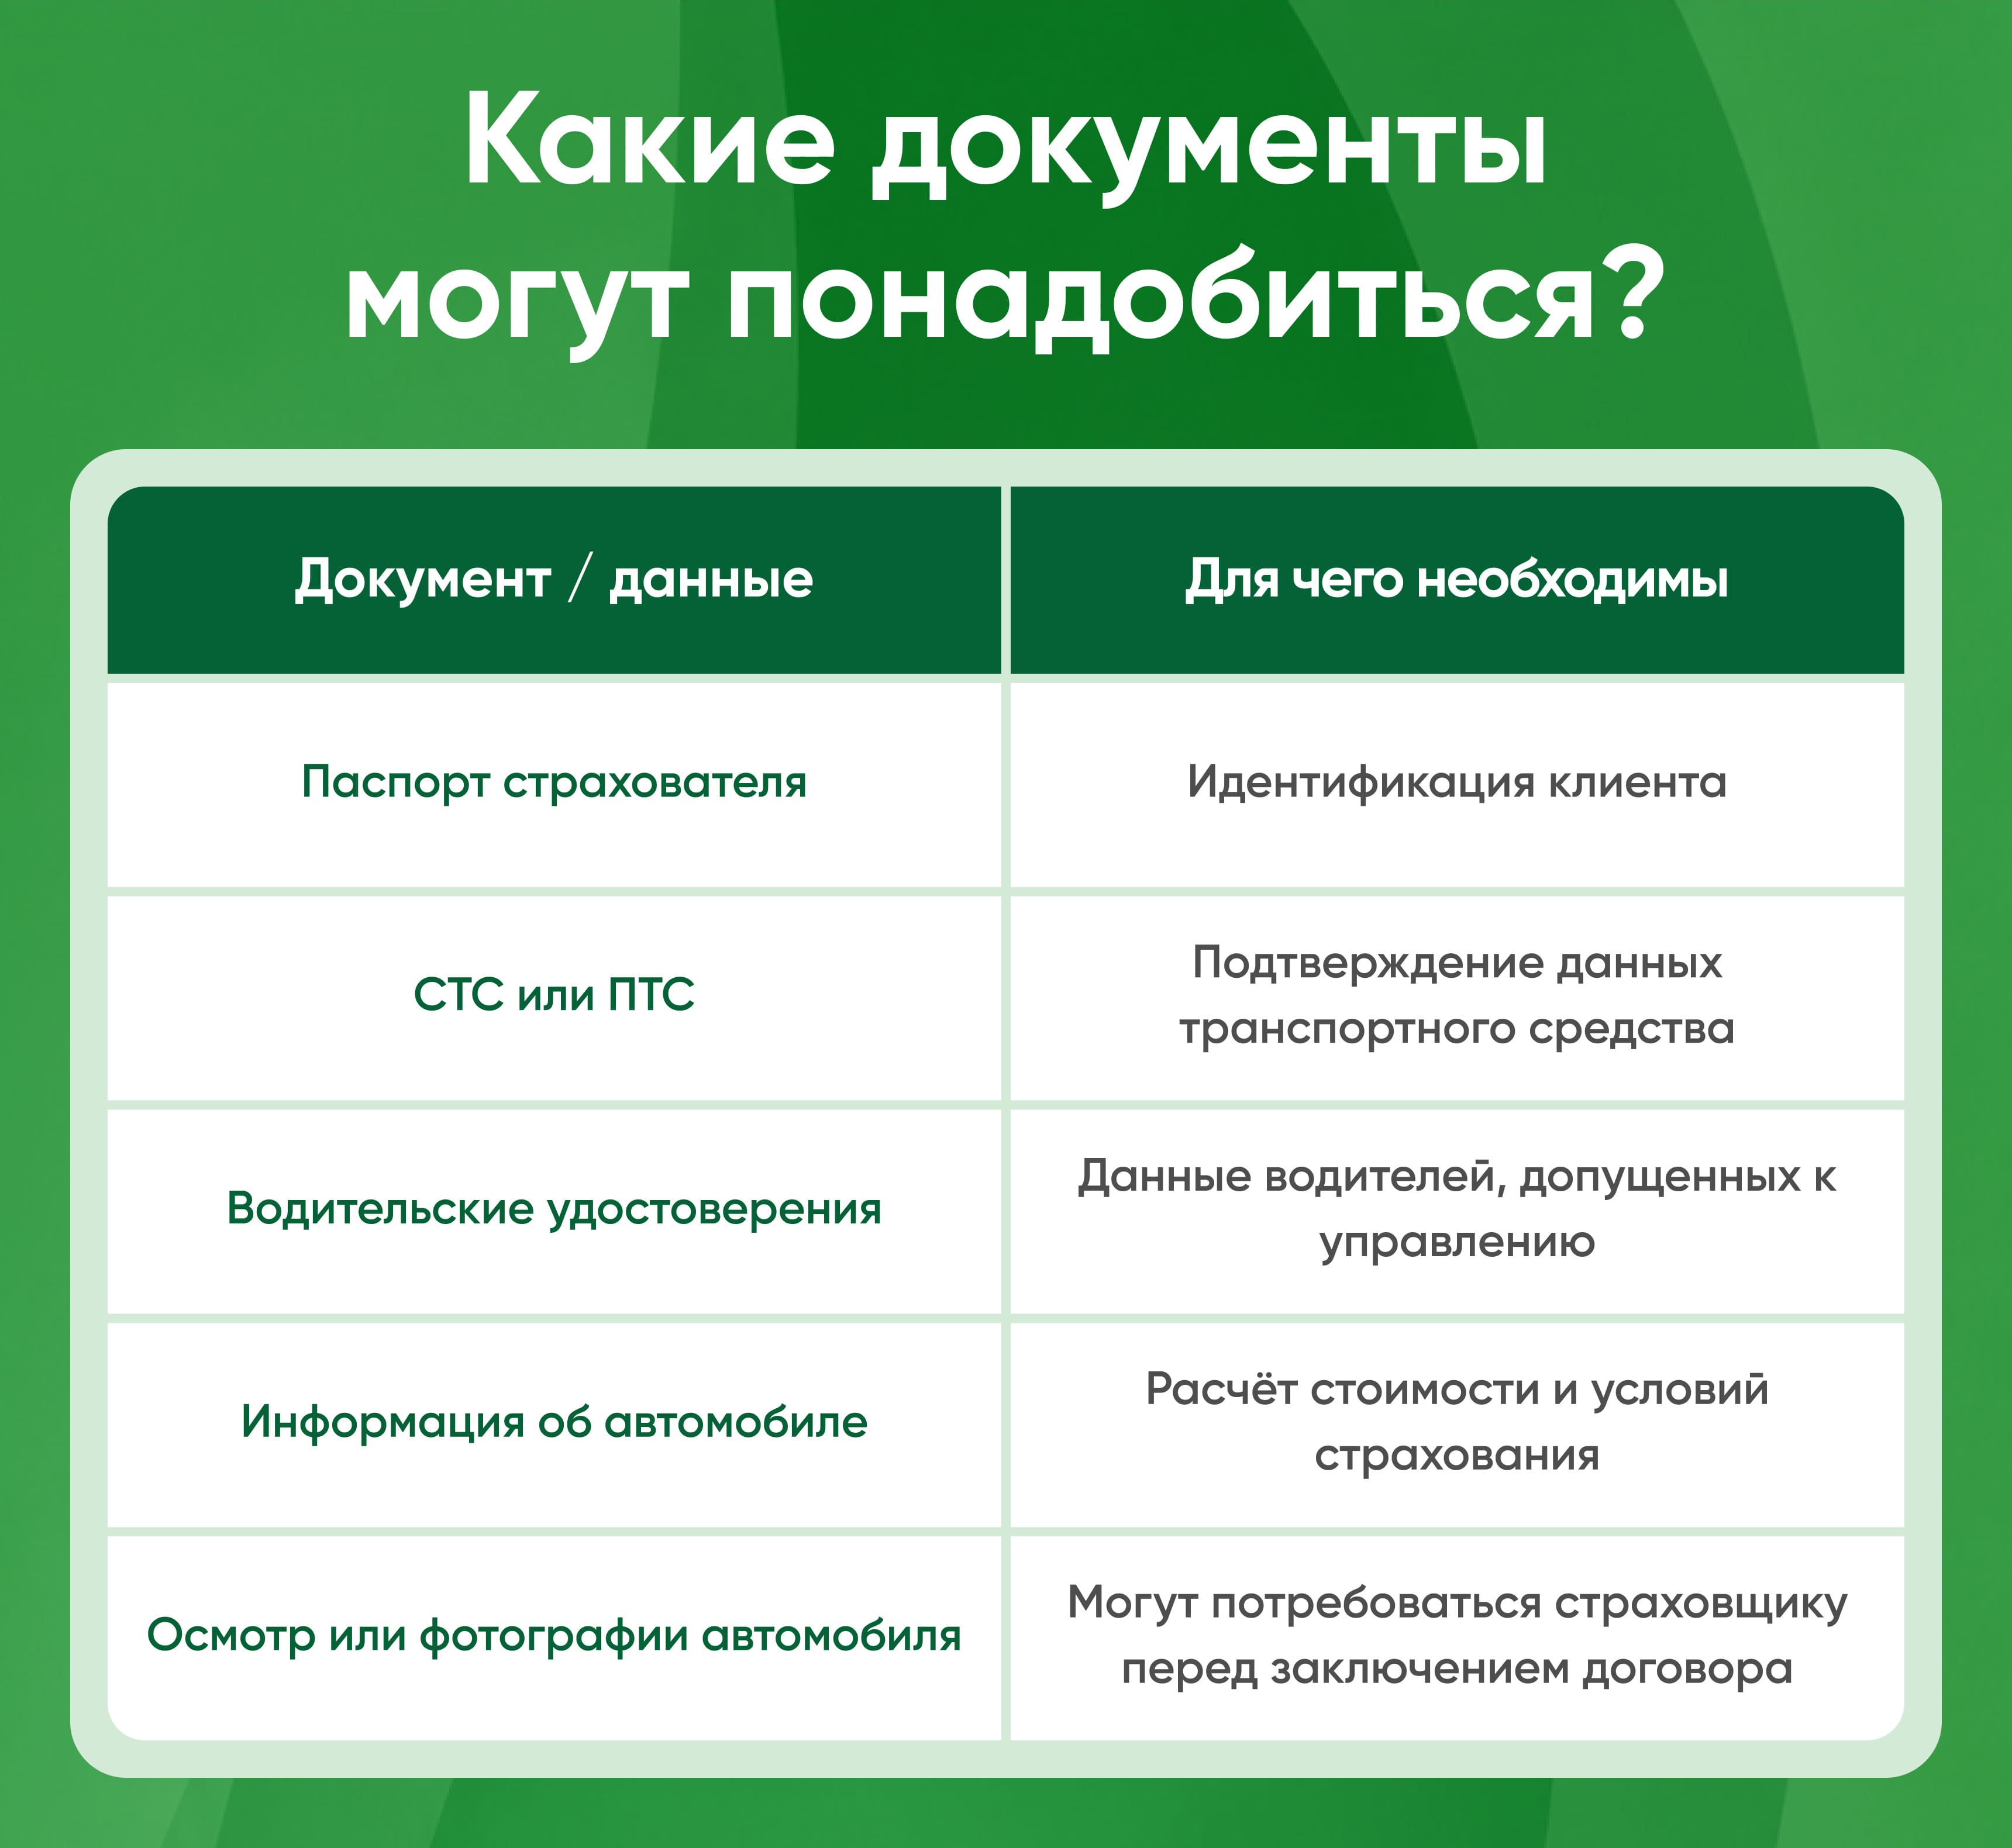
Some Russian insurers allow remote vehicle inspection via photos or through a mobile application.
Typically, the following are used during processing:
| Document / data | Purpose |
|---|---|
| Policyholder's passport | Client identification |
| Vehicle registration certificate or title | Vehicle data confirmation |
| Driver's licenses | Information on drivers authorized to operate the vehicle |
| Vehicle information | Calculation of insurance cost and terms |
| Vehicle inspection or photos | May be required by the insurer before concluding the contract |
Some Russian insurers allow remote vehicle inspection via photos or through a mobile application.
Who especially needs CASCO
CASCO can be useful for virtually any vehicle owner, but it is especially relevant in several situations.
First of all — for new and expensive vehicles, when even relatively minor repairs may require significant expenses.
Policy is also often considered by owners of financed vehicles. Depending on the loan terms, the bank may have its own requirements for insuring the collateral vehicle.
CASCO makes sense to consider for those who:
First of all — for new and expensive vehicles, when even relatively minor repairs may require significant expenses.
Policy is also often considered by owners of financed vehicles. Depending on the loan terms, the bank may have its own requirements for insuring the collateral vehicle.
CASCO makes sense to consider for those who:
- actively use the vehicle every day;
- travel frequently by car;
- leave the vehicle in open parking lots;
- want to protect against theft risk;
- are not willing to independently bear major expenses after a serious accident;
- want to receive additional protection beyond OSAGO.
How to get CASCO through GreenGo
For GreenGo partners, processing the new product is integrated into the familiar workflow on the platform.
The process is as simple as possible:
Thus, a partner can help the client obtain additional vehicle protection without sending them to independently search for a suitable insurance product.
The process is as simple as possible:
- Log in to your GreenGo personal account.
- Select the "CASCO RF" product.
- Enter the necessary client and vehicle information.
- Receive available insurance terms.
- Select a suitable option and complete the processing.
Thus, a partner can help the client obtain additional vehicle protection without sending them to independently search for a suitable insurance product.
Advantages of CASCO for GreenGo partners
The appearance of CASCO expands partners' capabilities in one of the key areas of auto insurance.
OSAGO covers the client's mandatory need, while CASCO allows offering additional protection for their own vehicle.
For the partner, this means:
At the same time, it is important not just to offer CASCO, but to explain to the client the differences between programs. One person needs maximum protection, another only major risks, and for a third, a deductible option is more cost-effective.
OSAGO covers the client's mandatory need, while CASCO allows offering additional protection for their own vehicle.
For the partner, this means:
- expansion of the product line;
- ability to work with owners of new and expensive vehicles;
- additional product for clients who are already purchasing OSAGO;
- ability to select insurance tailored to individual needs;
- comprehensive approach to vehicle protection;
- additional reason for the client to return.
At the same time, it is important not just to offer CASCO, but to explain to the client the differences between programs. One person needs maximum protection, another only major risks, and for a third, a deductible option is more cost-effective.
Summary
The appearance of Russian CASCO on the GreenGo platform expands partners' capabilities in auto insurance and allows offering the client protection not only for their liability but also for the vehicle itself.
CASCO can help reduce financial consequences of accidents, theft, total loss, natural disasters, and other unforeseen events — depending on the selected program.
For the client, this is an opportunity to select a level of protection based on vehicle cost, usage features, and personal budget. For the partner — another in-demand product that complements OSAGO and allows offering a more comprehensive approach to auto insurance.
CASCO can help reduce financial consequences of accidents, theft, total loss, natural disasters, and other unforeseen events — depending on the selected program.
For the client, this is an opportunity to select a level of protection based on vehicle cost, usage features, and personal budget. For the partner — another in-demand product that complements OSAGO and allows offering a more comprehensive approach to auto insurance.
How useful was this article?
Your opinion helps us become better.
Similar news
All
Partner network on GreenGo: how to build a team and earn more
Auto insurance
Health insurance
13 July 2025, 01:30
How to avoid mistakes when issuing a policy: data verification via PDF before payment
Auto insurance
Health insurance
16 July 2025, 02:45
OSAGO authenticity verification through NSIS: how the system works and why a partner should use it
Auto insurance
18 July 2025, 03:20
Stay informed of all news!
Starting in insurance is easier than it seems.
Subscribe to our Telegram channel and be the first to know about new opportunities for partners.
Join
Subscribe to our Telegram channel and be the first to know about new opportunities for partners.
Frequently Asked Questions
No. In Russia, CASCO is voluntary vehicle insurance. OSAGO, on the other hand, is mandatory.
No. These are different types of insurance. CASCO does not eliminate the obligation to have OSAGO when required by law.
Such coverage is possible. It all depends on the list of risks, exclusions, and other conditions of the specific CASCO contract. Some programs provide compensation for vehicle damage even in accidents caused by the policyholder.
Theft and hijacking may be included in the CASCO coverage. However, it is necessary to check whether this risk is included in a specific program.
Yes, on the Russian market there are programs with a limited set of risks, including options for protection against theft and total loss of the vehicle.
Total loss means a situation where the vehicle is destroyed or its repair cost reaches a threshold established by the contract, at which point repair is recognized as economically impractical. The specific criterion is determined by the insurance terms.
There is no universal answer. A deductible usually allows reducing the policy cost, but the client pays part of the loss out of pocket in the event of a claim. Therefore, the choice depends on the budget and the amount of risk the vehicle owner is willing to accept.